 搜索

 搜索
Global Hotel Brand Communication Report (Greater China) in August 2026
In August, demand for extended-stay accommodation surged, county-level markets saw an upgrade toward upscale hotels, and "school-seeing travelers" took over from family vacationers, boosting bookings around universities.
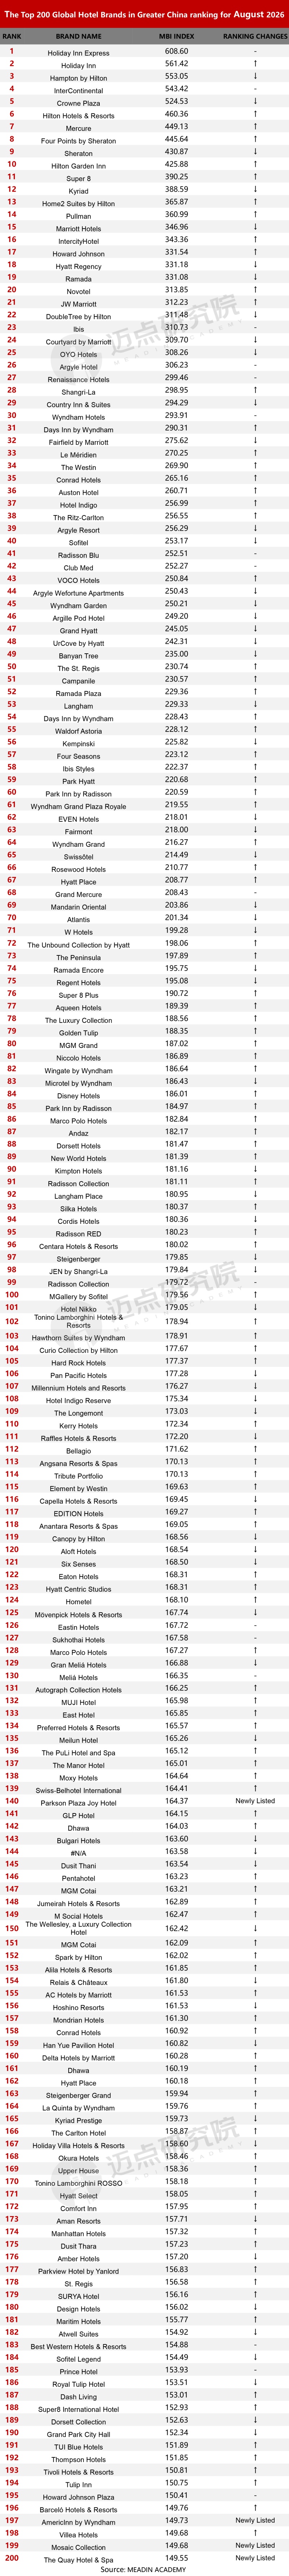
The Meadin Academy newly released the "Top 200 Global Hotel Brands (Greater China) Ranking for August 2026". Holiday Inn Express, Holiday Inn, Hampton by Hilton, InterContinental, Crowne Plaza, Hilton Hotels & Resorts, Mercure, Four Points by Sheraton, Sheraton ,and Hilton Garden Inn have all secured spots in the top ten of the list.
Key Data Interpretation:
1、Brand Dimension Analysis: The data shows that the average value of the TOP10 index is 500.29, the average value of the TOP100 index is 266.153, and the average value of the TOP200 index is 214.312. The average gradient index of the TOP10 shows a slight upward trend, while the averages for the TOP100 and TOP200 show a slight downward trend. Among them, the proportion of brands with an index of 500 or above is 2.50%, those in the 400-500 range account for 2.50%, those in the 300-400 range make up 8.00%, those in the 200-300 range constitute 22.00%, and those in the 100-200 range account for 65.00%. Among the top ten, the index of Holiday Inn showed significant month-on-month growth. As the mid-to-upscale business travel representative of IHG's Holiday brand family, Holiday Inn saw a wave of new property openings in late August, with the Holiday Inn Linyi Lanshan and Holiday Inn Ningbo Beilun opening one after another, driving up the brand's media index and investment index. Combined with the final push of the double-points promotion for stays before August 31 and the release of pent-up summer family travel demand, the brand's media exposure and review volume climbed in tandem, sending its index sharply higher month-on-month.
2、Group Dimension Analysis: Among the group brands, Marriott International,Wyndham Hotels & Resorts, Accor, InterContinental Hotels Group, Hyatt Hotels Corporation, Hilton, Argyle Hotel Group, Radisson Hotel Group, Banyan Tree Hotels & Resorts, and brands under Louvre Hotels Group ranked among the top ten by number of shortlisted entries. This month, the number of brands that Wyndham Hotels & Resorts has in the ranking increased by 1 (+1), and that of Hilton Hotel Group also increased by 1 (-1). It is worth noting that InterContinental Hotels Group performed outstandingly this month, occupying four of the top five spots (Holiday Inn Express, Crowne Plaza, InterContinental Hotels, Holiday Inn). Among them, Holiday Inn saw a 12.65% month-on-month growth in index, ranks first in growth among the top ten brands. InterContinental Hotels Group accelerates its expansion in China—August 2026 marks the 80th anniversary of the founding of the InterContinental brand. Under the theme of "Eighty Years," the Group has rolled out a series of global brand communications and member appreciation campaigns, with the buzz steadily spilling over into the Greater China market. Coupled with the market entry of new brands such as Garner Hotels, both its footprint and momentum in the region continue to climb. Group Brand Index—This month, the overall index of hotel groups showed a slight upward trend. Among them, 38.46% of the hotel groups saw an increase in index compared with the previous month, while 61.54% saw a decrease. The groups with the most significant increase were Centara Hotels & Resorts (17.51%), Parkside Hotels and Resorts (14.82%), and The Peninsula Hotels (6.38%). On the other hand, Kerzner International (-10.39%), Mandarin Oriental Hotel Group (-10.83%), and Kempinski Hotels (-13.99%) had more significant declines. Among them, Centara Hotels & Resorts signed a brand cooperation letter of intent with Lingnan Hotels this month. Its mid-to-upscale lifestyle brand, Centara Life, will be launched in China with plans to expand into key cities over the next three to five years, driving the group's index up to the top of this month's gainers list.
3、Key Market Trend Insights:
1) The accommodation market is shifting from "headcount expansion" to "length-of-stay-driven" growth, with extended-stay travel emerging as the main engine of summer growth. According to summer season data reports released by multiple OTA platforms in August 2026, the structure of accommodation growth is changing: Fliggy's domestic hotel room nights grew 66% year-on-year, while the share of Ctrip guests staying 2 nights or more rose from 38% to 64%. Tujia saw extended-stay orders of 7 days or longer grow 21% year-on-year, with orders of 15 days or more up about 30%. Unlike previous summers when "headcount was king," this round of growth has been driven primarily by longer stays — extended-stay packages, monthly rental rooms, and multi-night stay perks have become key supply for hotels capturing the "summer residency" demand.
2) County-level accommodation is upgrading toward the "upscale" segment, as county-town travelers move from "having a place to stay" to "staying well." Qunar data shows that in August, the share of orders for upscale hotels in county towns rose to 23%, with users born in the 1980s paying an average of RMB 526 per night for hotels in county towns. As consumption power among county-level travelers continues to climb, and with upscale hotels and branded chains expanding into lower-tier markets, the supply structure of county-level accommodation — once dominated solely by budget homestays — is being gradually reshaped into a multi-tier supply system.
3) As the summer season winds down, "college send-off" guests are taking over from family travelers, bringing an off-peak mini-boom to hotels near universities. Qunar data shows that in late August, booking demand for hotels and homestays within 3 km of universities in Hangzhou grew 81% compared with early August, with guests mainly families of 2–3 staying 1–3 nights. Other university hub cities — Nanjing, Wuhan, Beijing, Shanghai, Guangzhou, Xi'an, and Chengdu — benefited in tandem. As family vacation traffic tapers off, college send-off families have become the most certain "seasonal increment" in the late-August hotel market, with family rooms and properties near universities and transport hubs as the main beneficiaries.
The Top 200 Global Hotel Brands in Greater China ranking for August 2026 is as follows———
MEADIN Brand Index (MBI) - Brand Value Inquiry Platform
MEADIN Brand Index (MBI) mainly analyzes the brand's communication power on the Internet and mobile Internet from three dimensions: media index, comment index and investment index. This is a free data analysis service provided by the Meadin Brand Index Monitoring System (MBIMS), which is independently developed by MEADIN ACADEMY.
Calculation formula: MBI=a * MI+b * CI+c * II
Note: MBI refers to the MEADIN Brand Index (MBI data of a certain brand); a, b and c refer to the weighted coefficients in the system; MI (Media Index) refers to the media index; CI (Comment Index) refers to the comment index; II (Investment Index) refers to the investment index.
Note: Enterprises or individuals can refer to brand index data to monitor and predict brand development, but the MEADIN Brand Index does not fully represent its brand development.
(1) Media Index (MI): The number of positive news related to brands’ keywords reported by major media, mass media, industry media, and social media over a period of time.
(2) Comment Index (CI): The accumulation of user reviews on a certain brand’s properties on various OTA (Online Travel Agency) websites over a period of time.
(3) Investment Index (II): Over a period of time, the franchise and development status of a certain brand in the Greater China market, including cumulative opening status, new opening status, cumulative signing status, new signing status, urban coverage density, investment owner attention, etc.
MEADIN ACADEMY – Culture and Tourism Industry Data Center
MEADIN ACADEMY has been engaged in building a Culture and Tourism Industry big data analysis platform, utilizing "data productivity" to change cognition and improve enterprise efficiency. It provides diversified big data solutions based on intelligence, data, and services for enterprises and public institutions which are looking forward to entering and expanding culture and tourism and rental real estate businesses. Transforming numbers into facts, the platform assists enterprises in making important decisions and identifying investment risks.
0


